Technically reviewed 8 October 2026 · General information only, not personal advice. Read our disclaimer.
We turn down more prospects than we take on. If that sounds arrogant, give it three minutes, by the end I think you’ll see it the other way around.
Most firms don’t say who they wouldn’t work with. We will. We’ll tell you why, in writing, on a public page, because the kinds of work we say no to and the kinds of clients we’d send elsewhere describe this firm more precisely than anything we’d say yes to.
There’s a book a lot of accountants quietly own and almost none of them act on. James Ashford’s Selling to Serve makes a simple argument, and it’s the one sitting underneath most of what follows. Pricing accounting work isn’t extraction, it’s what enables the work to be done properly. Charge too little and you have to remove the things that make the work valuable. The proactive review. The structuring foresight. The second opinion before you sign anything. What’s left is compliance, dressed up as a relationship.
Ashford takes it another step, and this is the piece most firms skip. The engagement only works when both sides perceive the value. The prospect has to be able to see what the fee buys, not just be capable of paying it. When that two-sided perception is missing, the engagement fails, sometimes loudly, usually quietly, almost always at the client’s cost more than the firm’s.
So three flavours of “no” fall out of that. Here they are.
The first no: when the situation isn’t ready for us yet
There are perfectly good reasons not to need what we do. A straightforward compliance service may be the right fit for straightforward affairs, and saying so early is a kindness, not a judgement.
Our work is for owners who need us involved in the decisions as well as the returns, and the fee has to support that work. If you receive a proposal from me and find yourself questioning the fee against the value of the work, then I have not done my job properly: the fix is a better explanation or a better scope, not asking you to take it on faith. A high-volume compliance firm is built to lodge what’s in front of it, and for straightforward affairs that is exactly the right product at the right price. What it is not built to do is ring you in March to say your structure is leaking, or stop a trust distribution before it becomes a section 100A question. The fee they charge is honest, in the sense that it accurately reflects what the model is designed to do. It’s just not the same product as ours, and pretending otherwise is the kind of small dishonesty that builds up into a relationship neither side enjoys.
So if your turnover is around $80,000 and you’re a sole director doing your own books in Xero Starter, ringing us up about “tax planning,” the honest answer is that proper tax planning won’t pay for itself yet. Spend a few hundred on a clean BAS lodgement and a tidy tax return. Don’t spend several thousand on us yet. Come back when the structuring questions are real, when you’re at $400,000 of revenue with a couple of entities and a question that actually has stakes attached, and you’ll get more out of the conversation, and we’ll do better work for you because the conversation has weight.
There’s no shame in this no. It’s a sequencing problem, not a worth problem. Your situation isn’t lesser. It’s earlier.
The second no: when you can pay but you don’t want what we sell
This is the load-bearing one, and it’s the no most firms duck.
Some prospects can afford the fee and still aren’t a fit. They’re not bad people (this is important, because the temptation when you’re writing about clients you’ve turned down is to caricature them, and the caricature would be both unkind and inaccurate). They want to buy a different product than the one we’re selling, and they don’t quite know it yet.
Questions about the fee are welcome. What it includes, what it doesn’t, whether it can be fixed: we should be able to explain all of that, and if we can’t, that is our problem. What does not fit is an expectation that we will skip the checks, hide a problem, or sign something we cannot support, so that the price comes down. You can usually tell in the first call whether the conversation is about what the work needs or only about what it can be made to cost.
So if we say yes here, we’re agreeing to do something we don’t actually do. We’d be leaving out work the file needs, or charging for thinking they don’t value, and within twelve months one of two things happens, either we resent them for paying us less than the work warrants, or they resent us for charging more than the deliverable they thought they bought. Neither outcome serves anyone. Both are predictable from the engagement call if you’re listening for them, and we are listening for them.
Ashford’s framing is the cleanest version of this, and it bears repeating because it’s the framing the rest of the firm runs on. Undercharging fails the client. Not the firm. The client. Because charging properly is what enables proper service, and work priced below what it needs ends up with something left out, usually the part that would have mattered when something goes wrong.
So when we hear that conversation pattern, we say no on the call. Not in three weeks via a polite email (which is the firm-side equivalent of ghosting, and I don’t think much of it). We tell the prospect we’re not the firm for them, suggest a couple of names that do high-quality compliance work at higher volume, and wish them well. They almost always thank us. Some of them come back two years later having had the experience confirm what they didn’t want to believe at the time. That’s fine, we’ll have the conversation again.
The first no is the easy one. This second one is harder, because the cheque would clear. Saying no to a cheque that would clear is the difference between a firm that has a position and a firm that doesn’t.
The third no: right fit, wrong moment
Sometimes the fit is right and the timing’s off, and this one’s worth flagging because it gets confused with the first two when it shouldn’t.
You might be reading this and thinking it’s the soft no, the courtesy no, the polite “we’ll get back to you” no. It isn’t. The prospect is exactly our profile. The work would be good work. We’d still pause for one of three reasons:
Capacity. We’re a two-partner firm and we deliberately keep the client list small (this is a feature, not an apology, the boutique register only holds when the maths of the client list holds). If saying yes to a new engagement means a current client gets less of our attention this quarter, the answer’s no on principle, even when the new prospect would be ideal. We’ll often offer to revisit in three or six months when capacity is real again.
Lifecycle timing. A major change, a restructure, a sale, a marriage, can alter the scope. We may deal with the urgent decision now and leave the routine work until the dust settles, rather than bill twice for set-up work that the change will redo. Selling or restructuring soon is usually a reason to speak before the event, not a reason to wait until it is over.
Damage that’s already done. Sometimes a prospect comes to us mid-incident, an audit they hadn’t told their previous accountant about, a Division 7A loan that’s been sitting wrong for six years, a Section 100A position that’s already been queried. We’ll take the call, and a messy history is not a reason to say no; refusing to deal honestly with it is. Where the clean-up is large and specialised, say a multi-year dispute already in progress, the right move can be a remediation specialist who lives in that kind of work, with us alongside. More often we do the clean-up ourselves: that is what the free file review and the overdue returns work are for. You do not need a perfect file before you speak to us. You do need to be willing to get it right.
So this is the no with a calendar reminder, not a dismissal. The relationship doesn’t end on the first call. It just doesn’t start there.
Why publishing this list is good news
Here’s the part you might not expect, and it’s the part I want to put on the table because it changes how you read everything above.
A firm that says yes to anyone with a chequebook gives the next prospect the same yes you got. There’s no filter. There’s no position. There’s a marketing page that says “tailored solutions for your unique business” (a sentence that tells you very little) and an engagement letter that’s the same as the one before yours and the one after.
A firm that publishes its no list has to live with it. Once we’ve written this down on a public page, every prospect who comes in is reading it before they ring us, and that’s exactly the point. A good number filter themselves out. The ones who do ring know roughly what they’re walking into, which means the conversation starts at the position the website implied rather than at zero. Both halves win. And the work we do for the people who become clients is better, because we said no to the things that would have diluted it.
The other thing we get out of this, and this is the bit where I’ll say it plainly, is that we don’t have to pretend. There’s a particular flavour of dishonesty that creeps into accounting practice when you take everyone, where you smile through engagements you shouldn’t have signed, where the email is breezy and the file is heavy, and the client gets a slightly worse version of what we actually do because half of us is annoyed we said yes. Skipping that pretence is the upside. It’s better for our work, better for our clients, and (I’ll say this part without dressing it up) it’s a better firm to be partner in.
So we say no more often than we say yes. The clients we DO take are the ones we serve well. That’s the whole arithmetic.
Saying no to the wrong prospect is the cheapest way we know to keep saying yes properly to the right one.
If we say yes to you, it’s not because we needed the fee, it’s because the work is going to land, for both of us. That’s the only honest place to start a relationship that’s going to last more than a year.
If we say no, it’s not personal. It’s the same arithmetic, run in reverse, either the situation isn’t ready for what we do, or the engagement would ask us to leave out work it needs, or the timing means the urgent part comes first. None of those is about you as a person. All of them are reasons we’d rather you find a firm that’s right for the situation you’re actually in.
We’d rather lose your business at the front door than lose your trust at the back.
Citations + further reading
- Ashford, J. (2021). Selling to Serve: Sell Your Accounting & Bookkeeping Services with Unshakeable Confidence for More Than You Thought Possible (2nd ed.).
- Australian Taxation Office. Section 100A and reimbursement agreements, see PCG 2022/2 and TR 2022/4 for the trust distribution issue mentioned above. ato.gov.au
- Australian Taxation Office. Division 7A, payments and loans through your business (ITAA 1936 Division 7A). ato.gov.au
Raise higher.
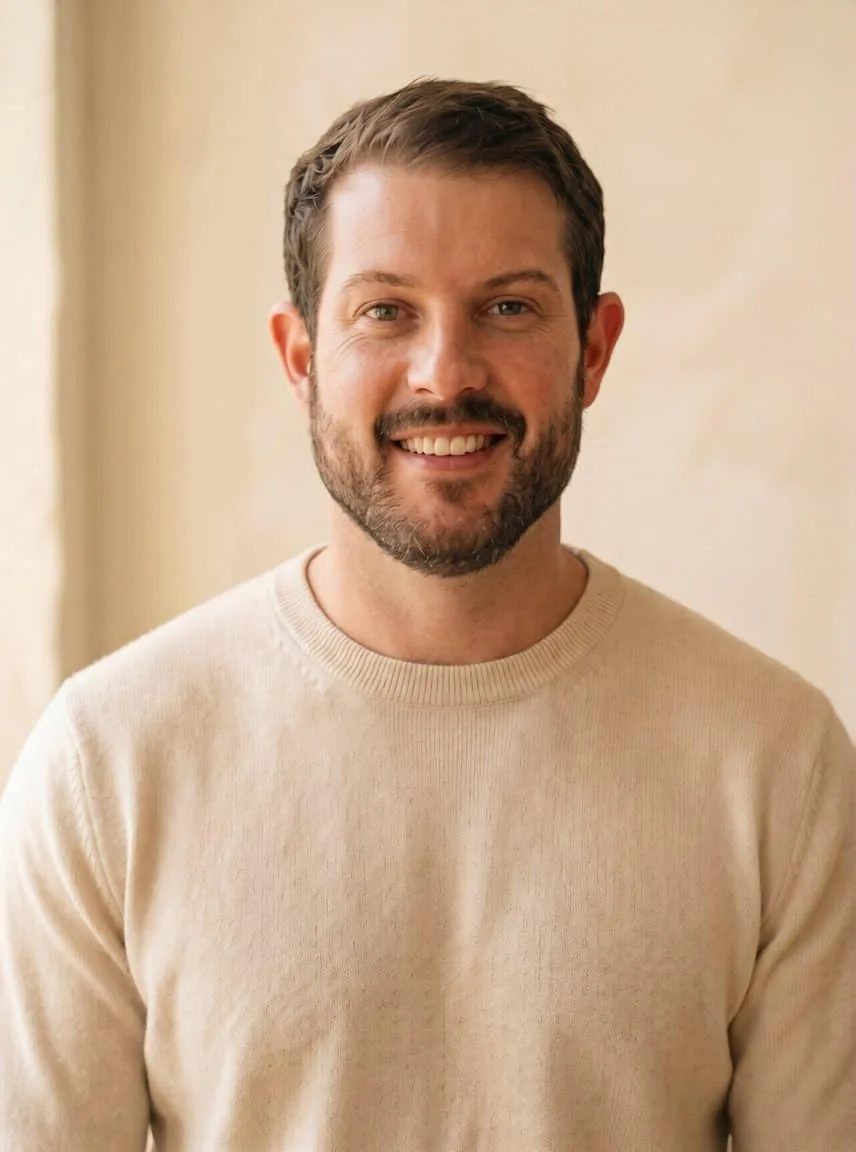
Written by
Byron Raal
Lead Accountant & Advisor, Altiora Advisory · Chartered Accountant (CA ANZ) · Registered Tax Agent 26 266 057
Byron leads the firm’s accounting, tax and advisory work. Clients deal with him directly throughout: the person who scopes the work, does it, and picks up the phone when something changes.
About Byron